Have you watched your kid at a checkout counter lately? You tap your phone against a payment terminal, grab your groceries, and walk away. To a seven-year-old, you didn't spend anything. You waved a glowing magic rectangle, and the store gave you food.
In our increasingly cashless world, physical bills have practically vanished from daily life. For children, money has turned into an invisible, infinite concept. When money feels invisible, the act of saving it feels completely pointless.
Recent research shows that parents want to change this dynamic. Over 50% of parents now introduce basic money concepts to their kids before age four.¹ That early start matters because a landmark study from the University of Cambridge revealed that our core money habits and attitudes toward waiting are mostly set by age seven.²
If we wait until high school to talk about money, we are playing catch-up. Greenlight reported that 75% of teenagers feel completely unprepared for personal finance.³ Teaching kids to save is about giving them autonomy and patience. It gives them the freedom to make choices rather than reacting to impulse.
Making Abstract Concepts Tangible with Visual Saving Tools
Young children think in concrete terms. When you tell a six-year-old that they have twenty dollars in a bank account, it means almost nothing to them. They cannot touch it, hold it, or watch it grow.
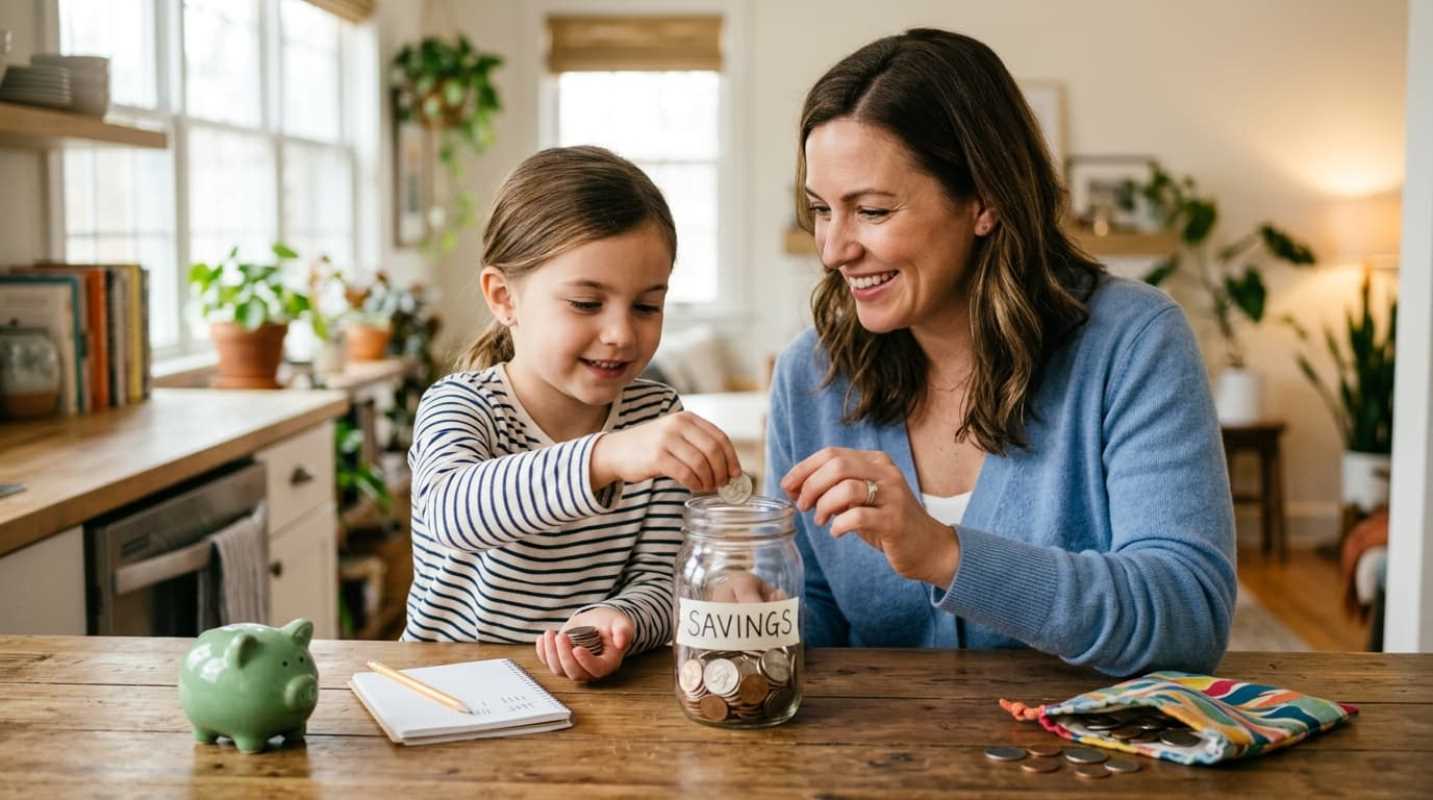
Clear containers change the equation completely. Traditional ceramic piggy banks hide coins away in the dark, which breaks the connection between saving and progress. With a clear plastic jar, your child physically watches the pile of coins climb higher each week. That visual feedback triggers excitement and reinforces patience.
A classic three-jar system gives kids a clear framework for every dollar they receive
• Spend: Discretionary cash they can use immediately for small treats or trinkets.
• Save: Dedicated funds for bigger goals that require weeks or months of waiting.
• Give: Money set aside for birthday gifts, community food drives, or animal shelters.
To make the "Save" jar even more compelling, tape a printed picture of their target purchase directly to the outside. If your daughter wants a twenty-dollar create kit, stick a photo of that exact kit onto the front of the jar.
For older kids, draw a thermometer goal chart on paper and stick it to the fridge. Every time they tuck away five dollars, hand them a marker to color in the next rung. You can even run a "Bank of Mom and Dad" matching program where you add a dollar for every ten dollars they keep in the jar at month's end. Real bank interest rates move too slowly for an eight-year-old to care, but your matching bonus makes compounding instantly obvious.
Smart Allowance Approaches Tied to Financial Literacy
Should allowance be tied to daily chores? Ask ten parents, and you will start a heated debate.
Some parents treat allowance like a wage where every dirty dish has a price tag. The problem with that method appears the moment your ten-year-old decides they don't need money this week. Suddenly, they opt out of walking the dog, and your system collapses. Other experts suggest treating allowance as an unconditional learning tool, completely separate from household duties.
A balanced hybrid approach works best for most families
• Baseline chores: Routine contributions like clearing the dinner table, making the bed, and picking up toys are unpaid duties. You do them because you are part of the family team.
• Educational allowance: A modest, predictable weekly sum given specifically so your child has actual money to manage, divide, and save.
• Extra paid gigs: Tasks outside regular duties, such as washing the car or clearing weeds from garden beds, earn extra cash.
A reliable benchmark for a base allowance is fifty cents to one dollar per year of age each week. An eight-year-old might receive six to eight dollars.
Most importantly, you have to give your kids the dignity of risk. If your son blows his entire monthly savings on cheap plastic junk that breaks two hours later, let him feel that disappointment. Do not replace the toy, and do not refill his jar. Experiencing a five-dollar regret at age eight protects him from running up thousands in credit card debt when he is twenty-five.
Differentiating Needs vs. Wants Through Real Choices
Kids are bombarded with targeted advertising on gaming platforms and streaming channels. To them, the latest video game skin or trendy water bottle feels like an absolute survival need.
Teaching the difference between needs and wants requires practice in real settings. Take your kids along on a routine grocery trip. Compare the store-brand cereal with the name-brand box sitting right next to it. Point out that choosing the store brand saves two dollars, and that difference can go straight into the family outing fund.
When your child begs for an impulse purchase at a retail store, implement the 24-hour rule
• Acknowledge the desire: Tell them the item looks fun without judging their taste.
• Take a photo: Snap a picture of the item on your phone so they know you won't forget it.
• Pause the purchase: Explain that if they still want to spend their own money on it tomorrow, you will bring them back.
Nine times out of ten, the urge evaporates by dinner.
You can also pull back the curtain on bigger household plans. If you are organizing a weekend camping trip or a trip to an amusement park, assign your child a specific portion of the budget to help with research. Ask them to compare ticket prices across different days or look up meal costs. When they see the math in action, they understand that saying yes to one thing means saying no to another.
Leading by Example and Modeling Healthy Financial Habits
Kids are perceptive observers. They absorb your emotional relationship with money long before they understand math. If every talk about bills involves tension and whispered arguments behind closed doors, children learn that money is scary.
Talk openly about your own financial goals. You don't need to share your exact salary or mortgage balance, but you can share your trade-offs. Let them hear you say, "We are skipping restaurant takeout this month because we are saving for new tires on the car."
Show them what intentional patience looks like in your own life. When you walk away from a purchase you wanted because it isn't in this month's budget, tell them. Seeing a parent wait patiently normalizes delayed gratification far better than any lecture ever could.
Keep your money conversations calm, encouraging, and focused on progress. By giving your kids hands-on tools, small decisions to make, and room to learn from their mistakes, you set them up for a lifetime of confidence.
Sources:
1. Teaching Kids About Money News
https://www.help.com/the-currency/money/teaching-kids-about-money-news
2. Money Habits Are Set By Age 7
https://www.calendar.com/blog/teach-your-children-well-money-habits-are-set-by-age-7/
3. Financial Literacy for Kids and Teens
https://greenlight.com/financial-literacy-for-kids-and-teens
*This article on Folloquy is for informational and educational purposes only. Readers are encouraged to consult qualified professionals and verify details with official sources before making decisions. This content does not constitute professional advice.*